FOR MINNESOTA CONSUMERS
Charged illegal fees on a cash advance?
Cash advance apps violate Minnesota law by charging high transfer fees. We handle the entire legal claim with zero out-of-pocket cost to you. Check if your cash advance is legal below and get up to $1,000 per illegal advance.
3 Steps
to Hold Predatory Lenders Accountable
STEP 1
Check Your Rates
Enter the advance amount, transfer fees, and repayment term into our calculator above.
What happens: The tool instantly calculates your true APR to show if your cash advance app violated Minnesota’s legal rate caps.
STEP 2
15-Minute Phone Review
Pick a time on our calendar that fits your schedule, and upload screenshots of 1 or 2 recent app advances.
What happens: We’ll review your transactions, confirm whether your app broke the law, and calculate your damages under Minnesota Statutes § 47.601.
STEP 3
We Fight, You Get Paid
Relax while we handle the legal process. in most cases, you never have to go to court.
What happens: We file your formal case or arbitration demand directly against the app. You pay $0 out-of-pocket and we only get paid if we successfully recover money for you.
Frequently Asked Questions
-
No. Your claim is filed directly against the third-party app or lending company (such as Payactiv, Homebase, or EarnIn), not your employer. Your employer is not a party to the claim, receives no legal notices, and has no involvement in the recovery process.
-
Under Minnesota Statute § 47.601, Subdivision 6, lenders who exceed state rate caps are liable for:
A full refund of all finance charges, express transfer fees, and tips you paid.
Statutory damages of up to $1,000 per violation (each individual cash advance counts as a separate transaction).
Payment of attorney fees and arbitration costs.
-
We represent Minnesota consumers strictly on contingency under Minnesota Rule of Professional Conduct 1.5. You never pay a retainer, write a check, or receive an hourly bill. Our fees and case expenses are paid entirely out of the settlement or statutory damages recovered from the lender. If we recover nothing, you owe nothing.
-
Most cash advance apps include mandatory arbitration clauses specifically designed to prevent consumers from joining large class-action lawsuits. This works to your advantage. We handle individual arbitrations directly on your behalf, which requires the app to pay substantial administrative and arbitrator fees just to respond to your statutory claim under Minnesota law.
-
Any app or online service that provided short-term funds before your payday and collected fees or tips from your Minnesota bank account. This includes active litigation targets like Payactiv and Homebase, as well as apps under active investigation such as EarnIn, Dave, Brigit, Klover, and MoneyLion.
-
Typically, no. You will not have to appear in a courtroom. The entire intake, document review, and settlement negotiation process is handled remotely via phone, email, and digital signature. If formal arbitration is necessary, all proceedings are handled directly by your legal counsel.
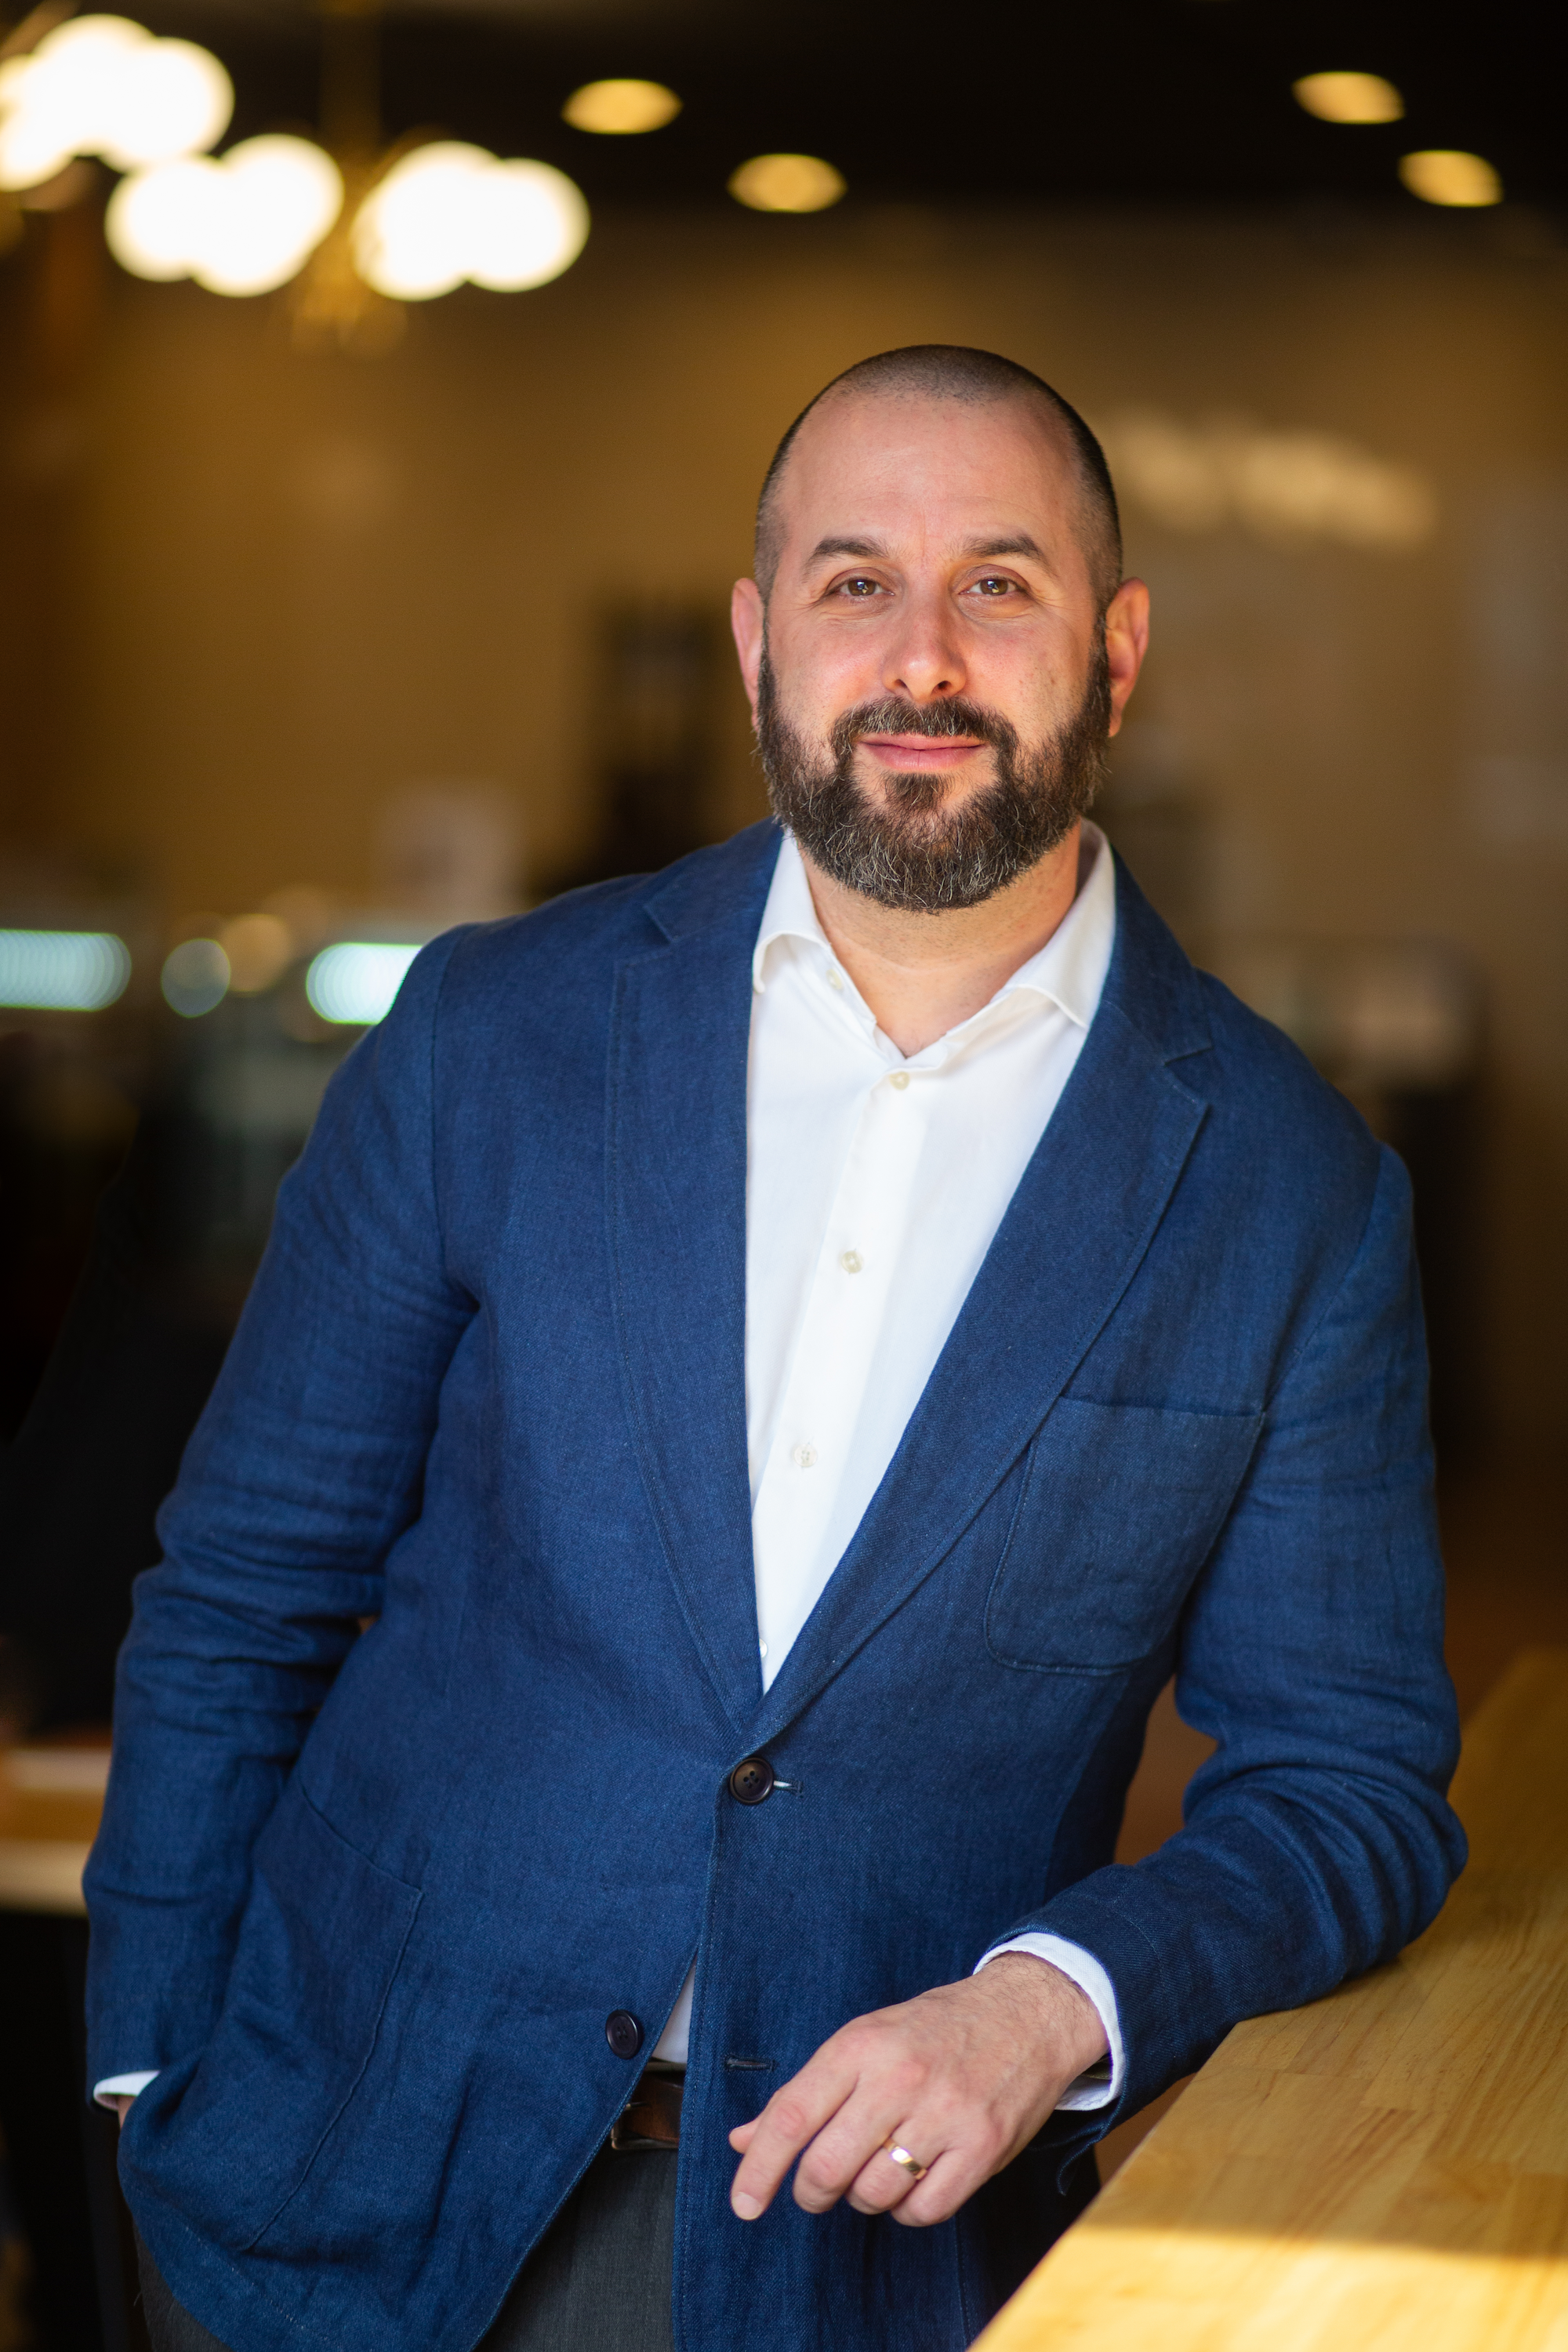
16 Years Fighting Predatory Financial Practices in Minnesota
A graduate of the University of Minnesota Law School, I spent years practicing law in Minnesota taking on banks and financial institutions that exploit everyday consumers.
My background dissecting financial ledgers and banking errors gave me an inside look at how lenders structure hidden fees. Today, cash advance apps market themselves as helpful tools while quietly charging effective interest rates exceeding 300% APR—directly violating Minnesota's statutory lending laws.
When you book a call, you speak with me. I personally review your app statements, calculate your damages under Minn. Stat. § 47.601, and pursue these lenders directly to recover what they unlawfully took from you.
David Friedman, Esq.
20 years of experience
Minnesota bar admissions: State and federal
Active Minnesota cases against Payactiv and Homebase.